


Published by: Elise Caradec — Editor specializing in exchanges and advice
Life insurance remains the preferred investment of the French, with a total outstanding over EUR 2 000 billion. Yet, behind this popularity are major disparities between the historical contracts of network banks, often charged with fees, and modern offers available online. To optimize your wealth, do not just open an account: understand the architecture of the contract, its taxation and select the mediums that can beat inflation over the long term.
How does life insurance really work?
Money placed on life insurance is never blocked. You can buy back at any time. The contract acts as a tax envelope in which you house different assets. There are two main types of media:
The funds in euro guarantees your capital. The year's interest is definitively acquired through the click effect. It is the secure support par excellence, whose yield has increased with the rise of the key rates. The Units of account (UC)On the other hand, there are no capital guarantees. You invest in financial or real estate markets. In return for a risk of loss, the performance potential is higher in the long term.
Life insurance offers great versatility. It allows for precautionary savings, the preparation of a real estate project, the generation of supplementary income for retirement or the transfer of non-inheritance capital under favourable tax conditions.
Selection criteria for a successful contract
To choose the best contract, do not stop on behalf of the sign. Three pillars determine the quality of life assurance over time.
Hunting for unnecessary expenses
This is the simplest and most impacting criterion. A modern contract must show 0 % fee on payments, 0 % of arbitration fees and annual management fees below 0.70% on units of account. Over 20 years, the difference between a contract charged for entry fees and a 0% offer represents tens of thousands of euros of lost profits.
The diversity of investment media
A quality contract offers an open architecture. You must access funds managed by different management companies, not just the insurer's home products. The best contracts today include ETF (trackers) to invest in low-cost stock exchanges, SCPIs for real estate, and sometimes Private Equity to further diversify.
Insurer strength and broker innovation
Life insurance is a long-term commitment. Choose a strong insurer associated with a responsive online broker, able to offer a smooth management interface and efficient automation options.
Free management or piloted management: which axis to choose?
The choice of management is often the first dilemma for savers. In free management, you decide on the distribution of your capital between euro funds and units of account. This is the ideal solution if you have financial knowledge and want to manage your allowance finely.
Piloted management delegates these decisions to experts. You define a risk profile — prudent, balanced or dynamic — And the manager adjusts the positions for you. This approach is suitable for those who lack time or confidence in their analytical capabilities. However, monitor the additional charges for this service as they can erode net performance.
Consider a hybrid approach: combine the two management modes. You can keep a contract in managed management for your portfolio core, while using a second contract in free management to experiment on specific topics such as technology or real estate. This method enables decision-making to be decorated and gradually learns about market mechanisms.
Taxation and transmission: major benefits
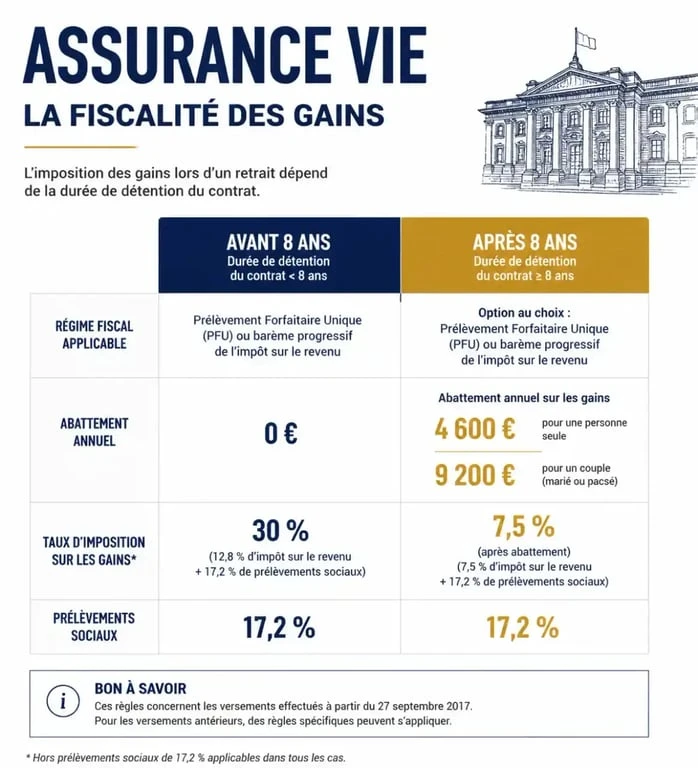
Life insurance benefits from taxation in tunnels. As long as you do not withdraw money, your earnings are not taxed, excluding social contributions from the euro fund. On redemption, only the share of earnings included in the withdrawal is taxed.
| Old contract | Taxation of earnings (Payments after Sept. 2017) | Annual allowance (Single / Couple) |
|---|---|---|
| Under 8 years | Single unit levy (SPF) of 12.8% + 17.2% PS | None |
| Over 8 years | 7.5% + 17.2% PS (up to 150 000 € paid) | 4 600 € / 9 200 € |
After 8 years, you get an annual discount on redeemed interest, often allowing you to withdraw significant amounts without income tax. It is an effective tool for generating complementary income.
In terms of estate, life insurance is a powerful instrument. For payments made before 70 years, each designated beneficiary may receive up to 152 500 € With no inheritance rights. This lever protects your loved ones and facilitates the transmission to people without a direct relationship, thus avoiding the 60% tax applied in the classic setting.
Luxembourg's alternative for large assets
For investors with significant capital, generally above 250,000 €, Luxembourg life insurance offers additional guarantees. It is based on two pillars:
The Security Triangle ensures that the assets of the customers are deposited in a depository bank independent of the insurer, under the supervision of the Luxembourg State. The Super Privilege guarantees that in the event of an insurer's bankruptcy, policyholders are first-tier creditors, ahead of the state itself.
Luxembourg contracts allow investment in a multitude of currencies and access to sophisticated media, such as custom-managed internal dedicated funds (FID). It is a solution of geographical and legal diversification popular with expatriates and wealthy families.
Conclusion: Make date today
Life insurance is a tool that must evolve with your goals. To succeed in your investment, choose online contracts without entry fees, diversify your units of account via ETFs to reduce costs, and do not wait until you have significant capital to take date. By opening a contract today, even with the minimum required, you launch the 8-year meter, an essential condition to benefit from optimal tax optimization in the future.