


Published by: Elise Caradec — Editor specializing in stock exchange
Transforming accumulated capital into a regular income stream is the goal of many savers. Whether you wish to anticipate your retirement or generate an immediate additional resource, the simulation of an investment is an indispensable step. It allows you to move from the project to the numerical reality, taking into account decisive variables: inflation, taxation and the lifetime of your savings.
Monthly pension mechanisms
Before starting a simulation, it is necessary to distinguish two modes of perception. The first option is based on the progressive consumption of your capital, called decumulation. The second is based solely on the interest generated, which preserves the initial amount for your heirs.
Life annuity or scheduled withdrawals
The life annuity is a contract with an insurer: you give it your capital in exchange for income paid up until your death, regardless of your longevity. It is a protection against the risk of living beyond your financial forecasts. In contrast, Scheduled withdrawals the withdrawal of a fixed sum each month from an investment. If you live longer than expected, the capital eventually runs out.
Impact of compound interests
In a simulation, the annual rate of return is the main engine. However, in an annuity phase, the calculation is inverse to the saving phase. Each monthly withdrawal reduces the basis for calculating future interest. A precise simulation must therefore incorporate a monthly calculation frequency in order not to overestimate the sustainability of your capital.
What capital to get a target rent?
The table below presents estimates of the capital required to generate different monthly annuities, based on net rates of return on management fees, before taxation. These figures are based on the assumption of maintaining capital, where only interest is withdrawn.
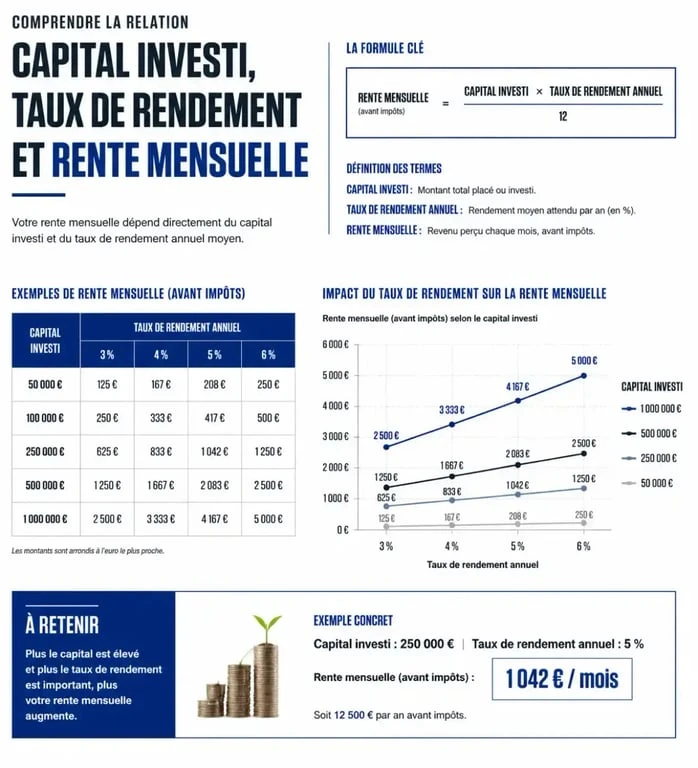
| Monthly rent | Capital (Percentage 2%) | Capital (Percentage 4%) | Capital (Percentage 6%) |
|---|---|---|---|
| 500 € | 300 000 € | 150 000 € | 100 000 € |
| 1 000 € | 600 000 € | 300 000 € | 200 000 € |
| 2 000 € | 1 200 000 € | 600 000 € | 400 000 € |
The rate of return is the most effective lever. Increasing from 2% to 4% yield makes it possible to divide the savings effort necessary to maintain the same standard of living.
3 strategic investments to generate revenue
Not all media produce the same results. Some focus on safety, others on performance or management simplicity.
Life insurance and scheduled buybacks
Life insurance does not require retirement. You can opt for Programmed partial buybacks. You thus keep your hands on your capital while benefiting from advantageous taxation after 8 years. Only the interest portion included in your withdrawal is taxed, which maximizes the net amount collected each month.
The Retirement Savings Plan (PER)
The RIP is designed for the retirement phase. It allows you to deduct payments from your taxable income during your working life. At the time of termination, you choose between a split capital outlay or a lifetime annuity. It is a suitable tool if you agree to block your funds in exchange for an immediate tax saving.
SCPIs for real estate income
The Civil Real Estate Investment Companies (SCPI) collect quarterly or monthly rents. This is a solution for those looking for an income indexed to real estate. By investing in tertiary parks, you delegate rental management while collecting income from many tenants.
Variables that influence your simulation
Too optimistic a simulation can lead to disappointments after a few years. Several invisible factors nibble the real purchasing power of your pension.
Inflation is the first factor. A pension of 1,000 € Today will not have the same purchasing power in 15 years. To maintain your standard of living, your simulation must have an indexation or a return above inflation of at least 2 points. Secondly, taxes vary according to the product. Between the Single Flat-rate Collection (SPF) of 30% and social contributions of 17.2%, the net amount may fall.
It is necessary to broaden your vision beyond the financial line. To consider its heritage requires the integration of distinct life phases: the first years of retirement, often more expensive, and the old age, which may require funds for dependency. A successful simulation is a curve capable of adapting to unforeseen circumstances, so that capital remains a dynamic tool at the service of your freedom.
The concept of « Safe Withdrawal Rate »
Popularized by financial studies, this concept suggests that removing 4% of its capital each year, adjusted for inflation, makes it possible to never exhaust its savings over 30 years. In a context of volatile rates, many analysts today recommend lowering this cursor to 3% or 3.5% for maximum security. It is a solid basis for reflection to simulate a perpetual rent.
Optimize your investment for maximum pension
To make the most of your simulation, a few management reflexes are needed:
- Diversify media: Don't bet everything on the fund in euros. Integrate a share of units of account, such as shares or real estate, to boost long-term returns.
- Watch the fees: Management fees of 1% per year on a life insurance contract can reduce your pension by 15% over 20 years. Favour reduced-cost contracts.
- Anticipate Reversion: If you are opting for a lifetime annuity, consider a reversion option to protect your spouse. This slightly reduces the amount of the pension but guarantees its financial security.
- Rebalance regularly: Your needs are changing, so are the markets. A simulation must be updated each year to adjust withdrawals based on actual capital performance.
Simulating a monthly pension placement requires rigour and a long-term vision. By combining several tax envelopes and staying cautious about the expected rates of return, it is quite possible to build a reliable and sustainable complementary income.