


Published by: Elise Caradec — Editor specializing in consulting
Updated on 23 March 2026
Better understand Life insurance rate Credit Agricole 2024 can really change the way you approach saving, even if the financial sector seems vague or difficult to understand: this year, returns are robust and accessible from 20 € for a child, 500 € for an adult. This facilitates the first steps towards an investment that combines the security of euro funds, attractive bonuses thanks to units of account, and significant tax advantages when examining the details of the discounts after eight years.
Some beneficiaries say that the transition from a classic booklet to life insurance has helped them diversify their savings without excessive risk taking, which really changes the trajectory of their family heritage.
Life insurance rate 2024 Crédit Agricole: key figures
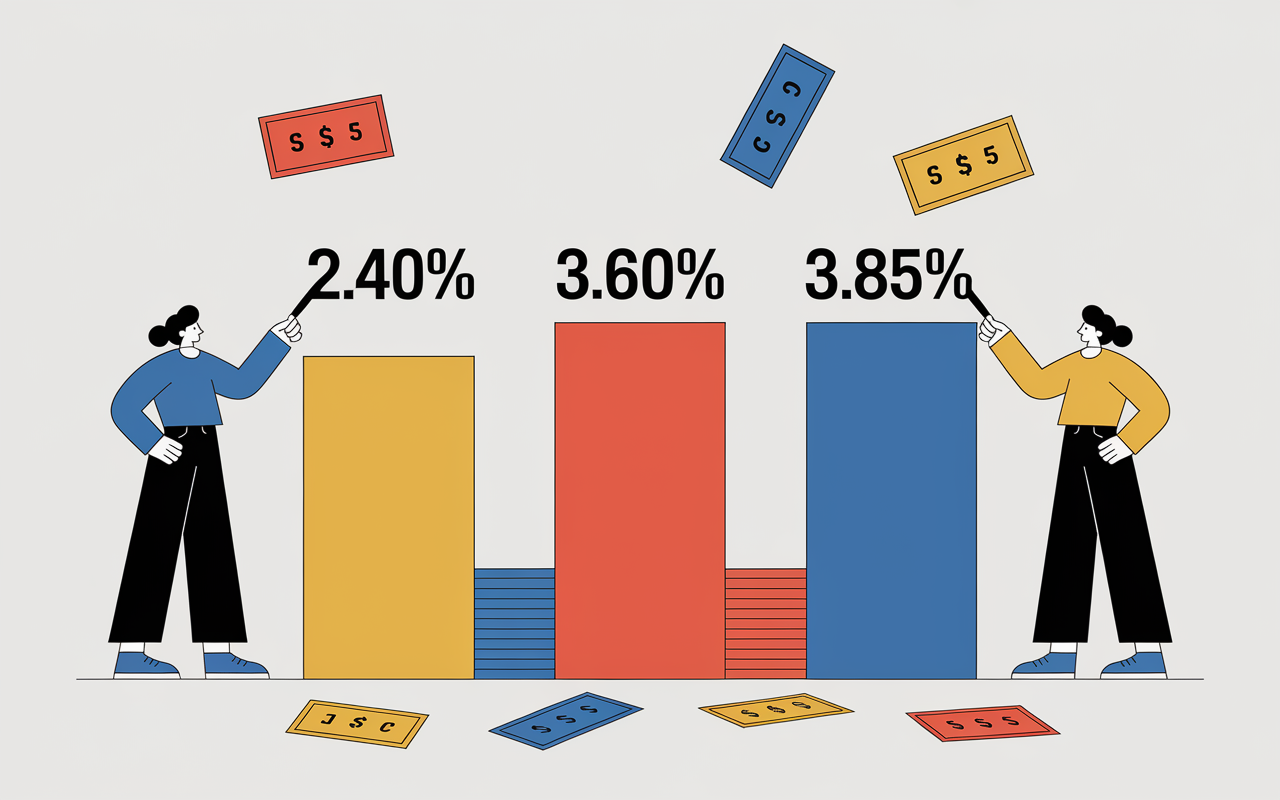
When you want to know the exact returns of Crédit Agricole life insurance contracts for 2024, the latest net rates communicated (excluding social contributions) deserve special attention. The fund in euros Predissime 9 proposes 2.40% base, and this profitability is supported by bonuses for profiles opting for units of account, up to 3,20 % maximum.
The Anae and Floriane 2 contracts remain very competitive, reaching 3,85 % if certain conditions are met. The average market rate is around 2.60 %, so that Crédit Agricole manages to exceed this benchmark thanks to its UC bonus policy (units of account).
| Contract | Basic rate 2024 | Maximum rate (UC bonus) | UC threshold for max |
|---|---|---|---|
| Predissimus 9 Sér. 2 | 2,40 % | 3,20 % | ≥ 50 % UC |
| Floriane 2 | 2,80 % | 3,60 % | ≥ 50 % UC |
| Anae | 2,95 % | 3,85 % | ≥ 50 % UC |
| Market (average) | 2,60 % | ||
Please note that all these rates are calculated after management fees and distributed on the Predica euro fund. Social security contributions still have to be taken into account. 17,2%. Access to the best rate usually implies a minimum of units of account: 30 and 50 per cent the contract. Opening starts as soon as 20 € for children and 500 € for adults, which facilitates a gradual entry.
Little trick to keep in mind: invest 20,000 € 3 per cent a year in theory 600 € Gross gain– a much more visible sum than a Book A capped at 3 % (and whose rate could decrease, according to several banking experts).
How do UC performance bonuses work at Crédit Agricole?
When Crédit Agricole's life insurance is considered, the security of the euro fund often comes first. But this year, the mechanics of unit of account bonuses make all the difference. The higher the UC distribution, the higher the rate. But then, what is the real functioning? Here are some concrete explanations.
Progressive UC bonus grid: instructions for use
The enhanced return is based on the percentage of savings invested in units of account (UC), which are more dynamic than the traditional euro fund. This tiered system allows access to higher rates depending on the tranche of UC chosen for each contract. For example, Predissime 9 Series 2 –
- UC allowance less than 30%: gets 2.40% as base rate
- Between 30 and 39% of UC: 2.80 % access
- 40 to 49% of UC: the rate rises to 3,00 %
- One 50% or more of the UC: unlocks 3.20%, which represents the maximum bonus
This calculation of the UC share shall be carried out on the value of the contract at 31 December. This system is also valid for Floriane 2 (base rate: 2.80%, bonus at 3.60%) and Anae (base: 2.95%, bonus: 3.85%). It should be noted that too frequent arbitration is not necessary: an annual allowance is sufficient. According to heritage trainers, this system mainly guides profiles that accept a controlled dose of diversification, without having to take big risks.
Concrete example of UC bonus in 2024
Let's take Anna, 53, who places 30,000 € on Predissimus 9. She chooses to invest 16,000 € on the Euro Fund and 14 000 € (a little over 46%) in UC. She then gets 3,00 % as a boosted rate for 2024, which represents 480 € Gross interest on the euro fund portion. This supplement is close to 180 € more the floor rate – while keeping part of its investment in a secure environment.
Some Crédit Agricole clients report that this blend allows them to combine growth and tranquility, even for a first investment.
Crédit Agricole comparison with market and competition
In 2024, it may be useful to compare the Crédit Agricole offer to large banks and competing platforms. The performance gaps are linked to both the bonuses offered and the allocation choices. It is therefore relevant to be interested in what makes Crédit Agricole specific this year.
Analysis of rates and bonuses compared to the national average
The average market rate remains at 2.60 % for euro funds: Crédit Agricole exceeds this threshold once the contract includes more than 30 % of units of account. Most other banks oscillate between 2,30 and 3,00 %. Temporary boosted offers do not reflect the real market over time.
- On Predissimus 9, the rate rises up to 3,20 %, a significant increase of 0.6 points from the average
- Floriane 2: can reach 3,60 % in some cases
- Anaea: until 3,85 % by UC distribution
- In terms of online management, the leader Meilleurtaux offers a bonus of 5 % for a limited period (2026); However, most payments are stable around 3 % in practice
Crédit Agricole favours profiles that carefully diversify their UC contracts, while maintaining a solid basis on the euro fund. An asset management advisor points out that access to ISR media, particularly with Anaé, attracts many investors who are sensitive to the balance between return and ethical criteria.
Client returns and financial analysts
The notices published on Trustpilot or MoneyVox regularly highlight the reassuring management of contracts, despite the complexity that UC bonuses can represent. Several clients insist: « Getting 3% guaranteed from the euro fund elsewhere is almost out of reach. »
A user reports that she has hesitated to engage on UCs: it is not always obvious, but the gain can justify the approach when comparing with a Book A or the classic PERs.
All include costs and taxation of Crédit Agricole contracts
To choose in an informed way, it is better to anticipate the costs and taxation of Crédit Agricole products, in order to estimate the real net return once all the charges have been applied. It is also an opportunity to question certain ideas received during an interview.
The applicable fees at Crédit Agricole in 2024
Let us look at the main items to be monitored when we study Crédit Agricole contracts:
- The payment charges are based on 2.5% to 3% (standard, but online offers are generally lower)
- For the annual management of the euro fund, count between 0,60 % (Preliminary) and 0,96 % (Florian 2)
- UC fees are similar or even lower; certain ISR media involve own internal costs (see Chi/KIID in detail)
- Finally, the cost of arbitration is generally 0,5 %and sometimes free of charge at the first annual arbitration
Some contracts can be opened from 500 €, or 20 € for minors. This attracts many parents wishing to introduce their children to heritage management. It is assumed that the bank is in the high range of costs, but compensates for the stability enjoyed and a wide range of funds.
A financial advisor strongly recommends personalized simulation to refine net profitability according to your profile: it is a reflex that can avoid disappointments.
To anticipate your savings choices, discover the forecasts of return life insurance fund euro 2024 what performance hope and how to choose well.
To diversify your investments while taking advantage of the 2024 life insurance rate returns, discover also the Crédit Agricole shares opinions: benefits, limits and concrete returns.
To maximize your returns in 2024, it is essential to understand the subtleties of a Life insurance unit of account: operation, benefits and risks.
The tax framework and life insurance allowances
Life insurance offers an advantageous tax system: after 8 years, you have an annual discount of 4 600 € (person alone) or 9 200 € (couple) interest withdrawn.
Interests are subject to social contributions of 17.2% account entry. The rates of return displayed are net of management fees but remain calculated before social levies and income taxes (for a buy-back beyond the discount).
Imagine a client investing 10 000 € 3 per cent for 8 years: upon arrival, 2,590 € Gross earnings are accumulated, most of which can net out of tax if you meet the reduction limit (excluding social contributions paid each year). Some experts note that this flexible taxation is among the most advantageous in the heritage market.
FAQ, testimonials and interactive tools to choose in confidence
Many profiles still hesitate before starting. In order to answer the common questions, here is a compilation of the most recurrent questions in training, accompanied by feedback from knowledgeable users.
Common questions about life insurance rates Crédit Agricole
Let's look at the main questions/answers that clients regularly raise:
- The Predissimus 9 rate in 2024 range from 2.40% to 3.20% depending on the proportion of UC retained at 31 December.
- Get maximum bonus requires to place at least 50 % the contract in UC at the end of the year.
- The rates are net of what? They are net of management fees; social contributions (17,2 %) and possibly income tax.
- Minimum amount at subscription? 20 € for one child, 500 € for an adult ; Some counsellors adapt start-up according to the family context.
- The obligation to use? It does not exist, but without UC, access to the best rates is not guaranteed.
- ISR and real estate support: Yes, they are available upon subscription, especially on Anaé, or via arbitration. Some clients report that discovering the ISR component during an interview was decisive in their choice.
To illustrate: Claire (58 years old, CA Lyon manager) shares that she started with caution, then raised the UC share to 45 % From 2023: « I wouldn't have imagined reaching 3% on my pension savings by staying in a regular bank! ». Several savers say that they adjust their profile annually to meet the new bonus opportunities.
To optimize your choices, the use of Crédit Agricole Assurances simulator allows you to estimate your earnings in a few clicks. It is also wise to compare on sites known as MeilleurTals, in order to print a summary to be submitted during a consultation.
Does this tool really make a difference? According to several trainers, the ability to anticipate its net after fees and taxes reassures customers, especially those engaged in long-term wealth management.
You can simulate your return or download the official PDF of 2024 rates according to your needs. If uncertainty remains, do not hesitate to ask the advisors or ask the question in comment: the right reflex today may open up new perspectives for tomorrow!