


Published by: Elise Caradec — Editor specializing in exchanges and advice
The Equity Savings Plan (EAP) is a preferred tool for investing in European stock markets while benefiting from advantageous taxation. However, its operation is strictly regulated by the Monetary and Financial Code. Unlike an ordinary security account, the PEA is based on the principle of uniqueness. Mastering the rules of detention is essential to optimize your heritage strategy and avoid forced closure by the tax administration.
The uniqueness rule: only one conventional APE per taxpayer
The law is clear: every adult can only hold one Traditional PEA. This limit applies regardless of the financial institution chosen, whether it is a traditional bank, an online bank or a specialized broker. It also covers all forms of plans, whether bank or insurance.
For tax purposes, the AEP is linked to the individual and not to the tax home. If you live as a couple, each ACAP spouse or partner can open their own plan. On the other hand, it is strictly forbidden to increase openings in different institutions in order to try to circumvent the payment ceilings.
Management in the Tax Home
In a married or married couple subject to joint taxation, the household may hold up to two conventional PEAsone per spouse. Minor children or older children attached to their parents' tax homes cannot open a traditional PEA. However, they benefit from a specific option, the PEA Young, designed to allow them to take a fiscal date before their financial autonomy.
Changing bank: the transfer procedure
If your current intermediary is no longer suitable for you, do not open a second plane elsewhere. The legal procedure is the transfer of PEA. This transaction moves your securities and liquidity to a new institution while maintaining the fiscal anteriority of your envelope. While this may involve fees, it is the only method authorized to change managers without closing your plan.
The cumulation allowed: Classic PEA, PEA-SME and PEA Young
If it is impossible to possess two conventional PEAs, the legislation allows for the cumulation of different variants. This flexibility allows investors to increase their investment capacity under tax envelopes.
All about how the EAP works and benefits · Discover the official rules and conditions for investing in a European stock portfolio through the Share Savings Plan.
The link between conventional PEA and PEA-SMEs
The PEA-SME is a complementary envelope for financing small and medium-sized enterprises as well as medium-sized enterprises (ETI). At the same time, you can hold a conventional PEA and a PEA-SME. This cumulation increases your overall investment ceiling while retaining the capital gains tax exemption after five years of holding.
PEA Young for 18-25 years
The Young AEP is intended for adults aged 18 to 25 who are attached to their parents' tax homes. It allows you to take a tax date from the beginning of your working life. Once the young person leaves the parental tax home, his Young PEA automatically turns into a classic PEA, thus retaining all the seniority acquired.
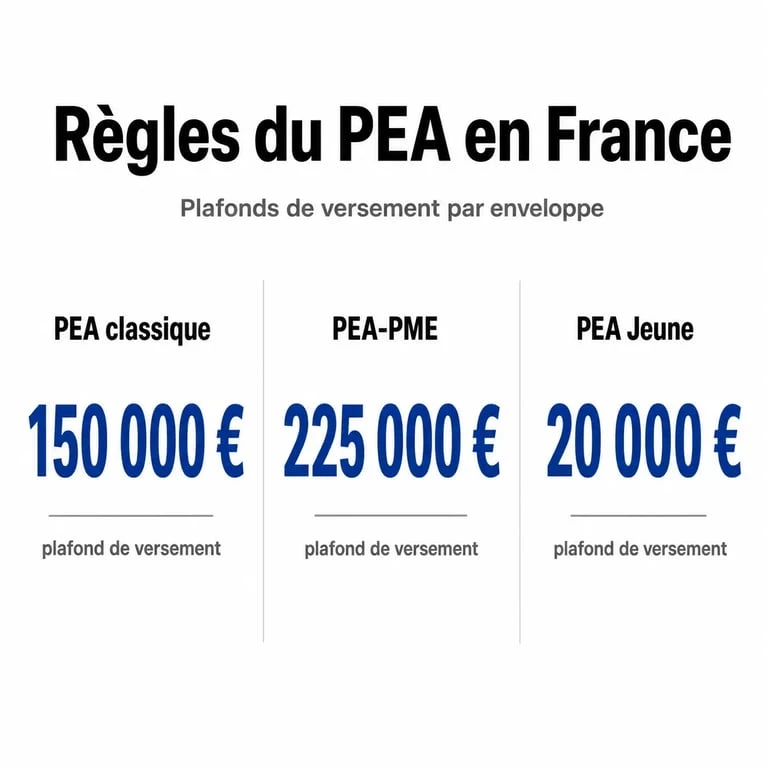
The characteristics of each plan are as follows:
| Type of Plan | Authorized | Payment ceiling |
|---|---|---|
| PEA Classic | 1 per adult | 150 000 € |
| PEA-SMEs | 1 per adult | 225 000 € |
| PEA Young | 1 per attached young person | 20 000 € |
The overall ceiling in case of cumulation
Although the cumulation of the PEA and PEA-SME is permitted, it is subject to a global payment ceiling. You cannot add the two ceilings without restriction.
The legislation requires that the total payments made on these two plans by the same holder shall not exceed 225 000 €. If you pay 150,000 € on your conventional PEA, your PEA-SMEs remittance capacity is mechanically limited to 75 000 €. Conversely, if you do not use conventional PEA, you can pay all of the 225 000 € on a PEA-SME.
For a married or pacse couple, the total capacity of the home is doubled. They can theoretically pay up to 450,000 € in all their four planes, respecting the individual breakdown of the ceilings.
Penalties for non-compliance
The tax administration closely monitors compliance with the uniqueness of the AEP. Each opening is reported to the Bank Accounts File (FICOBA), making any attempt at illegal multi-detention immediately detectable.
The consequences of an infringement are severe:
- Automatic closing all detained PEAs, including the foreground open plan.
- Loss of tax benefitmaking all earnings from origin taxable on income tax and social contributions.
- Penalties and increases applied by the tax on amounts due.
Before opening, check that you do not have an old plan forgotten in another bank, even with a minimum payment.
Practical questions about managing your accounts
Can we transform a PEA into PEA-SMEs?
No, there is no transformation bridge. These are two separate envelopes. If your traditional PEA is already saturated, you need to open a new PEA-SME with your intermediary to continue investing in SMEs with advantageous taxation.
What happens to the PEA in case of death?
Upon the death of the holder, the PEA is automatically closed. Securities are transferred to an ordinary securities account in the name of the estate. The tax benefit ends on the day of death: earnings made up to that date are exempt from income tax but remain subject to social levies. Future gains will be taxed under the common law system.
What about tax non-residents?
It is possible to keep its PEA opened in France after a transfer of tax domicile abroad, except to a non-cooperative State or territory. However, a non-resident cannot generally open a new AEP. The rule of uniqueness remains: if you already have one, you cannot open a second one, regardless of your country of residence.