


Published by: Elise Caradec — Editor specializing in consulting
Choosing an investment at La Banque Postale requires aligning your financial targets with the available tools. Between the security of regulated booklets, the fiscal flexibility of life insurance and long-term preparation via the Retirement Savings Plan (PER), the offer allows you to respond to every step of your life. To optimize your savings, it is necessary to exceed the facial rates and understand how each product links with your projects, whether it's financing a real estate purchase, protecting your loved ones or valuing capital.
Precautionary savings solutions: security and liquidity
Precautionary savings form the basis of your heritage strategy. At La Banque Postale, this category includes products with guaranteed capital and immediate availability. These materials are adapted to deal with unforeseen events or to finance short-term projects.
Regulated Booklets: Booklet A, LDDS and SARA
The Book A is the most used placement. With a rate fixed by the State and a total exemption from taxes and social contributions, it allows to place up to 22,950 €. The Sustainable and Solidary Development Booklet (LDDS) complete this device with a ceiling of 12,000 €while financing the social economy.
For households with modest incomes, the Popular Savings Booklet (LEP) offers superior performance. Its rate, higher than that of Book A, effectively protects your purchasing power against inflation, although its ceiling is limited to 10,000 €. Finally, the Young Booklet is accessible to 12-25 year-olds to initiate initial budget management.
The Booklet Account (CSL) for Unlimited Savings
Unlike the regulated booklets, there are no limits on payment in the Postal Bank's Booklet Account. This is a useful folding solution when your A and LDDS booklets are complete. Note, however, that the interest generated is subject to the Single Flat-rate Collection (SPF) or income tax, which reduces the net return compared to the debilitated booklets.
Life insurance at La Banque Postale: a customised management tool
Life insurance is a versatile heritage lever. It enables long-term capital to be valued while benefiting from an advantageous tax framework, especially after eight years of detention.
The transition from a flow saving, based on regular payments, to a stock saving, consisting of capital to be optimised, is a key step. At this stage, the arbitrage between secured euro funds and units of account, which are more exposed to market fluctuations, becomes decisive. The Bank Postale accompanies you to define this tipping point and avoid letting funds sleep on low yield media if your investment horizon allows a controlled exposure to financial markets.
Management and diversification
Bank Postale offers two ways of managing its life insurance contracts. The free management allows you to choose for yourself the distribution between the fund in euros, which guarantees the capital, and the units of account, composed of shares, bonds or real estate. The Management under mandate delegate the selection of supports to professionals according to your investor profile, whether it is prudent, balanced or dynamic.
Taxation and transfer of capital
Life insurance offers advantageous taxation in case of redemption. After 8 years, you get an annual discount on interest income of 4,600 € for one person alone, or 9 200 € for a couple. In terms of estate, this product allows the transfer of non-inheritance capital within advantageous limits, facilitating the protection of your beneficiaries.
Investing in markets and preparing for the future
If you accept a risk share to aim for a higher gain, Postal Bank offers investment solutions in financial markets as well as products dedicated to retirement.
The PEA and the securities account
The Share Savings Plan is the preferred tool for investing in French and European companies. After 5 years, earnings are exempt from income tax, excluding social contributions. The ordinary title account offers complete freedom in terms of geography and sector, but without any specific tax advantage.
The Retirement Savings Plan (PER)
The PER allows you to anticipate income decline at the end of your professional career. Its major advantage is the deductibility of voluntary payments from your taxable income, within the limits of the statutory limits. It's a lever to reduce your immediate tax burden while building up a capital or pension for your retirement.
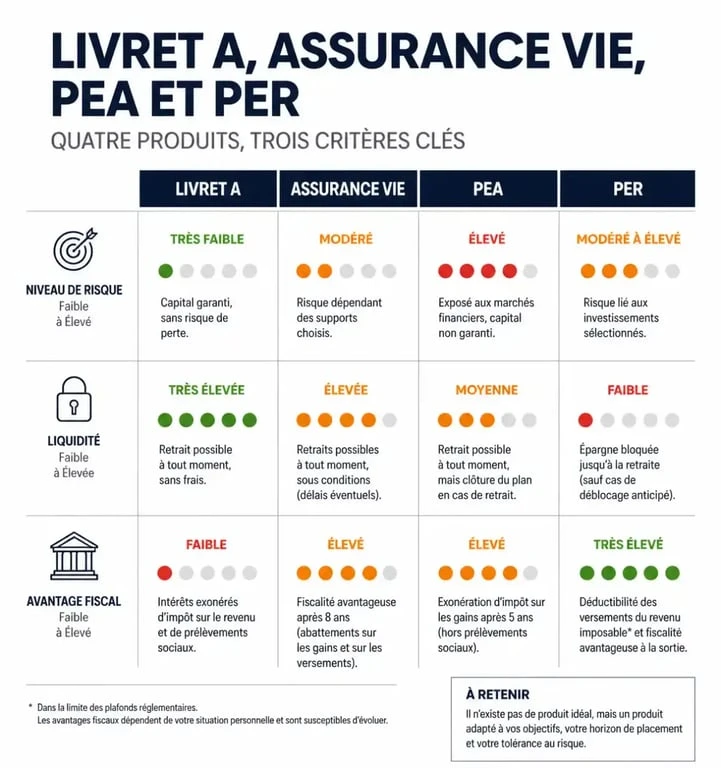
Comparison of major investments
| Type of placement | : 24/7 customer support is ideal, especially if you trade at unusual times. | Risk | Tax advantage |
|---|---|---|---|
| Booklet A / LDDS | Immediate | None | Total exemption |
| Life insurance | Quick (repurchases) | Variable | Allowance after 8 years |
| PEA | Variable (5 years recommended) | High | Exemption after 5 years |
| PER | Blocked until retirement | Variable | Entry tax deduction |
How to choose the right placement according to your profile?
There is no ideal placement in the absolute, but solutions tailored to your needs. To make the right choice at La Banque Postale, follow a rigorous methodology.
Define your investment horizon
Your investment horizon is the length of time you can immobilize your savings. For a short-term project, such as buying a vehicle, focus on booklets. For a long-term project, such as preparing for retirement or the future of your children, life insurance or PEA are more suitable. The longer the horizon is, the more volatile assets you can integrate to smooth the risk over time.
Assess risk tolerance
Before you subscribe, ask yourself what temporary value loss you can handle without panic. Bank Postale offers profiling questionnaires to determine whether your profile is prudent, balanced or dynamic. This step avoids closing an investment at the wrong time when markets fall.
The importance of personalized support
The strength of La Banque Postale lies in its network of agencies and the availability of its advisers. An appointment allows you to make a complete heritage report. Your advisor ensures that the chosen investment is integrated into a comprehensive diversification strategy, thus avoiding concentrating all your assets on a single medium. The online management via your customer space allows you to follow the evolution of your investments independently.