Published by: Jean Bogle — Editor in Chief
Buying SCPI shares on credit allows you to invest in real estate without immediately mobilizing all the capital. Distributed revenues contribute to the repayment, but they never guarantee the balance of assembly. To decide, it is necessary to compare monthly payments to income after taxation, to preserve a cash reserve and to ensure that the loan remains bearable if distributions decline.
Borrowing to buy shares: a lever, not guaranteed self-financing
A civil real estate investment company acquires and manages real estate assets for its partners. You buy shares and collect, when the results permit, a fraction of the income. The management company deals with buildings and tenants; you remain responsible for the repayment of your loan.
Compared to the cash purchase, the credit allows a large amount of money to be invested earlier while keeping part of its savings. In return, it adds interest, possible insurance and financing costs. It also reduces your ability to borrow for other projects, including a principal residence.
Leverage effects increase both earnings and losses. A real estate return above the cost of financing is a good thing, but comparing the distribution rate with the nominal rate of the loan alone is not enough. Taxation, fees, holding time and resale price of units determine the actual result.
The mutualization between several buildings and tenants limits the dependence on a single tenant. However, it does not remove the risk of income decline or capital loss. At least one detention 10 years is generally recommended, with no guarantee of resale at this time.
Calculate the monthly budget before looking at the return
The first calculation is simple: pre-tax savings effort = monthly loan payment - cashed distributions. To know the actual levy on your budget, add insurance if it is invoiced separately, taxes and any charges. The announced distributions are not necessarily the net amounts you will keep.
A numerical simulation and its degraded scenario
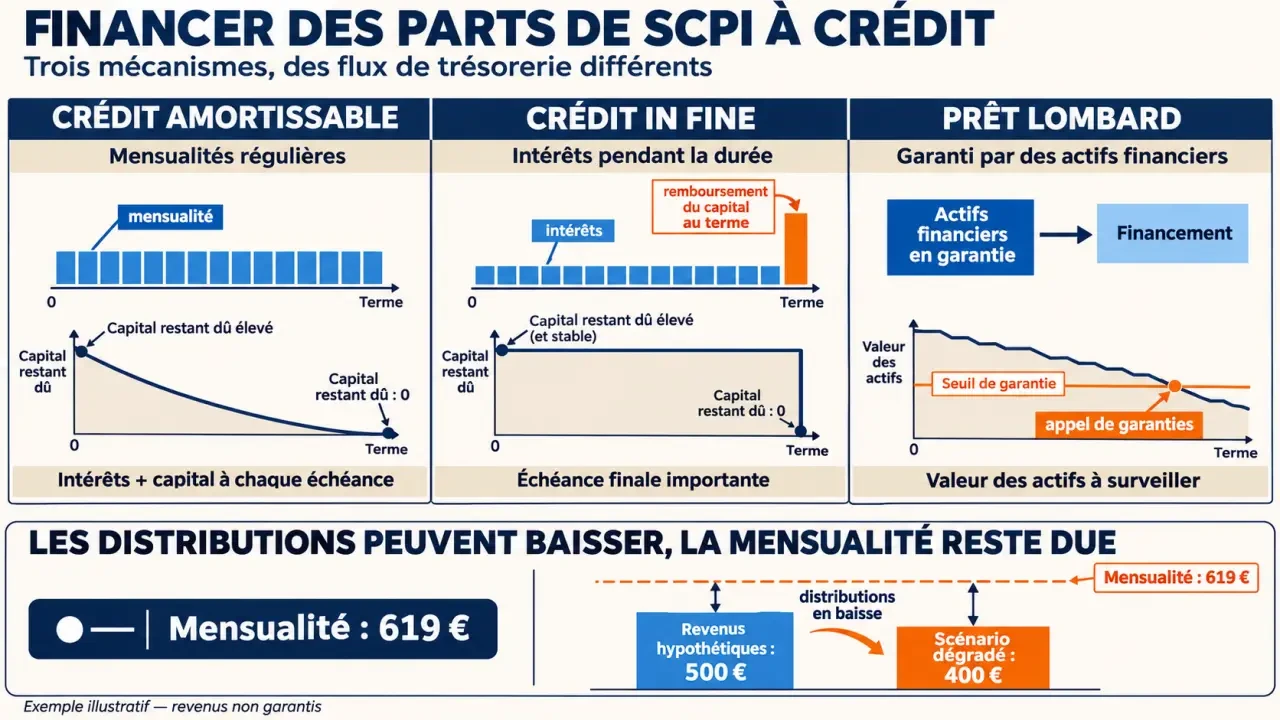
Let us take an illustrative hypothesis: 100,000 € borrowed over 20 years at a fixed nominal rate of 4.25%, excluding insurance and fees. The monthly payment represents about 619 €. With an assumed annual distribution of 6%, revenues equivalent to 500 € per month. This yield is a hypothesis, not a forecast.
| Situation | Equivalent monthly income | Effort before tax and insurance |
|---|---|---|
| Hypothetical distribution of 6 % | 500 € | 119 € |
| Distributions down 20% | 400 € | 219 € |
| Temporary lack of distribution | 0 € | 619 € |
In this case, the maturities total approximately 148 600 € over 20 years, of which approximately 48,600 € interest, excluding insurance and expenses. In cash, these interests disappear, but the 100,000 € are immediately mobilized. An honest comparison must therefore also incorporate the future of retained savings and the same tax and real estate assumptions.
Think of cash as a tablecloth covering the whole table: an annual average may seem sufficient while leaving an open corner. Quarterly distributions do not coincide with monthly bank payments. Add the waiting period, during which the newly subscribed shares do not yet generate income: a dedicated reserve must cover these lags, regardless of the yield displayed.
Choose the credit by how to repay the capital
Good financing depends less on the name of the loan than on your ability to repay its capital. Longer duration generally reduces monthly payments, but increases the total cost. A fixed rate secures maturities; a variable rate is exposed to their evolution, according to contractual terms.
Understanding the resale of SCPIs despite pending requests · Find out why the resale of SCPI shares can be difficult and what risks the AMF is associated with this investment.
| Financing | Operation | Primary surveillance |
|---|---|---|
| Depreciable credit | Progressive repayment of interest and capital | Monthly to bear even without distribution |
| Credit in fine | Interest during the loan, capital repaid on term | Final capital to be prepared upon subscription |
| Assigned consumption credit | Loan explicitly intended for the purchase of shares | Duration and sometimes less favourable cost |
| Lombar loan | Borrowing guaranteed by financial assets | Possible decrease in the value of guarantees |
At a fixed rate, depreciable credit offers stable monthly payments, with a decreasing interest share and a growing share of capital. It is a legible solution for building a heritage.
Final credit often requires investment in life insurance, initially representing 20 to 30 % the amount borrowed according to the installation. This guarantee does not mean that the final repayment is insured: the capital formation path must be checked.
The Lombard loan, often proposed on 1 to 4 yearsassumes an existing financial asset. Its short term is difficult to reconcile with the low liquidity of SCPIs without another repayment solution. A decrease in the wealth of assets may lead to the demand for additional guarantees.
Integrating taxation without overestimating tax economy
In the case of shares held directly and property income taxed to the real regime, interest on a loan allocated to their acquisition is in principle deductible, subject to the applicable rules. Some borrowing costs may also be incurred. The repaid capital is not deductible. Keep the loan contract and proof of allocation of funds.
The deduction reduces taxable income: it does not fully reimburse interest paid. Its interest depends in particular on your marginal tax rate, i.e. the rate applicable to the upper portion of your income. With a depreciable loan, interest gradually declines; The tax advantage can therefore decrease while monthly payments remain stable.
The SCPIs invested abroad require a separate calculation. Foreign real estate income generally does not support French social security contributions. 17,2 %, according to their qualification and the applicable tax treaties. However, they can be taxed abroad and influence French tax. The imputation of interest must be verified country by country: « European » does not mean « without tax ».
Preparing a file that also resists the bad years
The minimum amount financed is usually around 50 000 €, with offers sometimes accessible from 10 000 € or 20,000 €. Funding without contributions may exist, but depends on the file, the guarantees and the SCPI accepted. Banks examine your income, your existing credits, your remaining living and your available savings.
As a dated benchmark, francescpi reported rates as at 15 January 2026 from 4.15% over 15 years and 4.25% over 20 years. These indications are not a current offer. SCPI rates are often higher than those of a principal residence; especially compare the TAEG and total cost, insurance and expenses included.
- Collect proof of income, tax notices, bank statements, credit tables and statement of assets.
- Compare several offers and check the restrictions on financial SCPIs.
- Read the information documents: fees, waiting times, risks and withdrawal conditions.
- Ask for a post-tax simulation, with lower revenues and delayed resale.
Finally, look at the borrower insurance: in the event of death, it can cover the remaining capital due according to the guarantees, exclusions and insured quotas. It does not automatically cover the entire family debt. Before signing, require a complete schedule and careful projection: the project must remain sustainable without depending on rapid resale or constant distributions.